
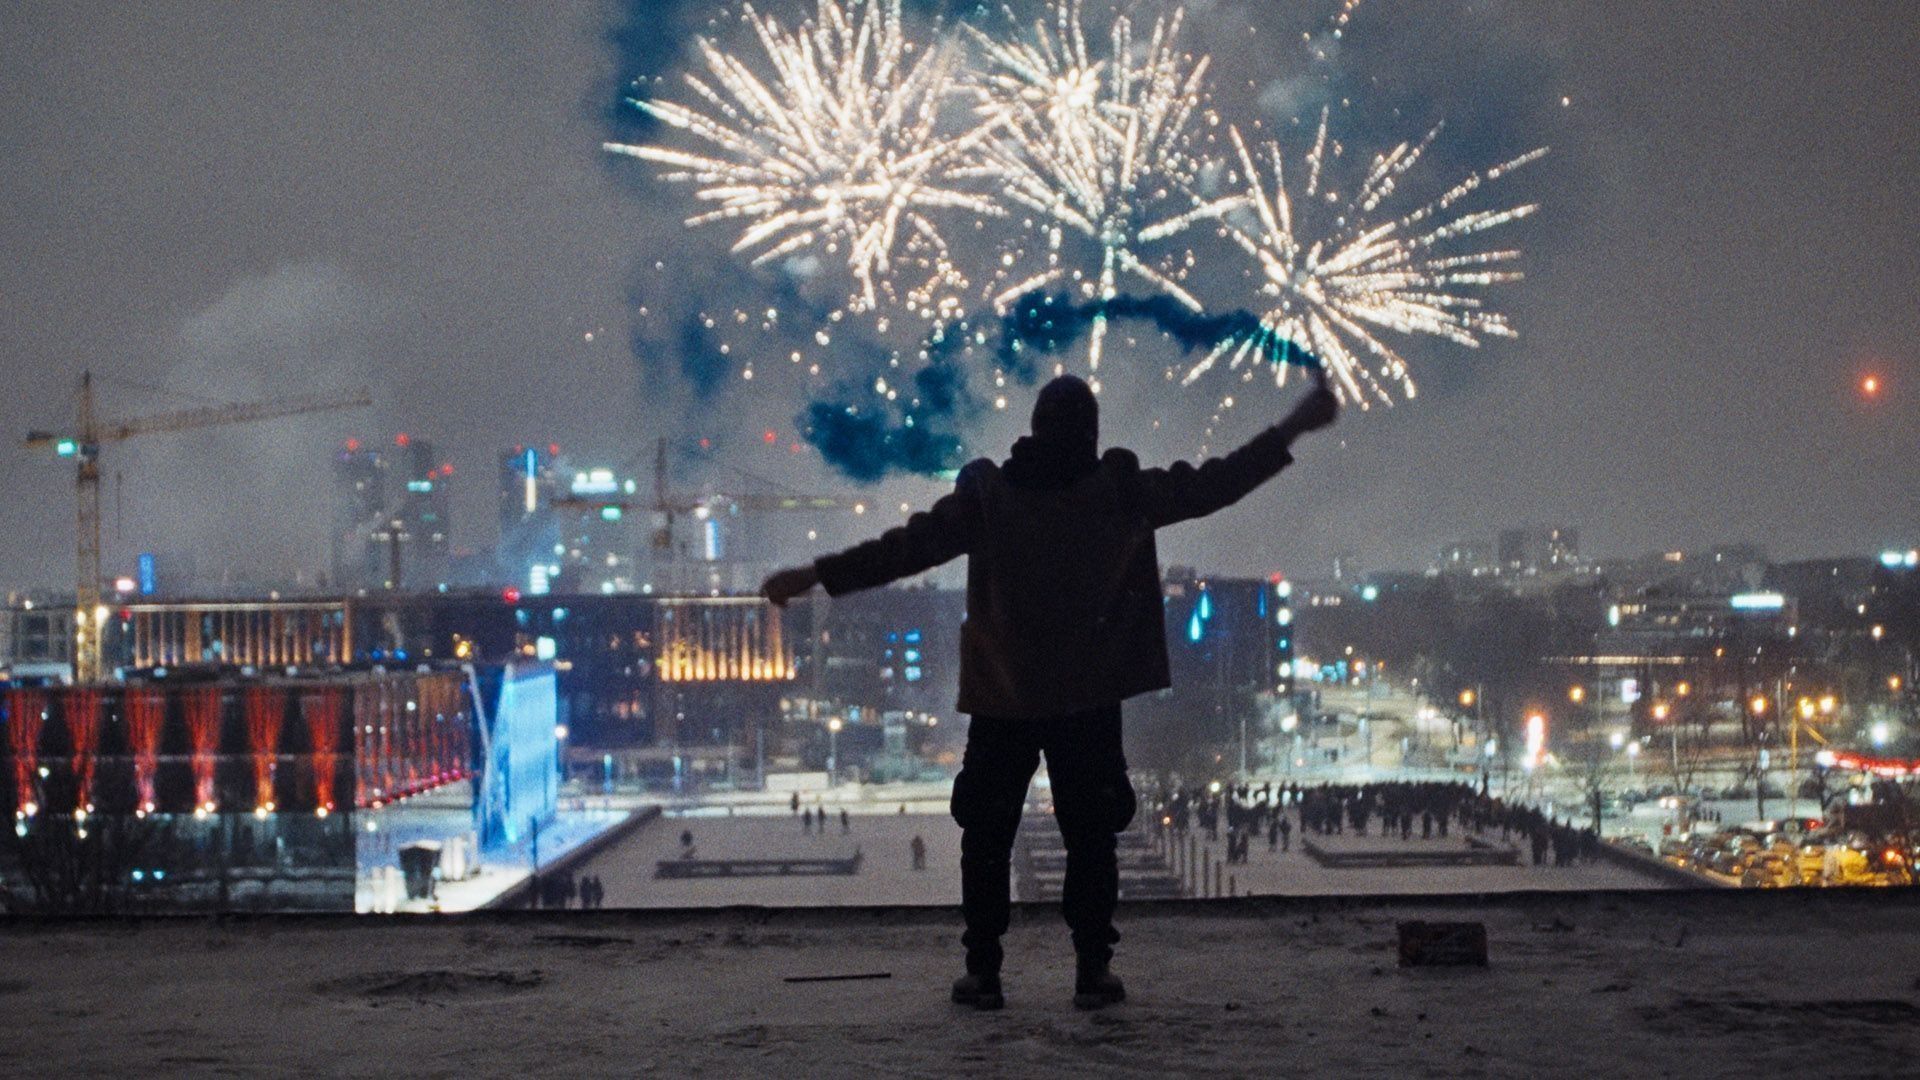
Baltic cinema is having its moment, and there are plenty of reasons for celebration at the 30th Tallinn Black Night Film Festival - but can the three small nations build a cohesive film industry?
When the Tallinn Black Nights Film Festival celebrates its 30th edition this November, it will place Estonia, Latvia and Lithuania at the centre of the programme and its industry-strand Industry@Tallinn & Baltic Event through a dedicated Focus: the Baltics. The choice is more than an anniversary gesture. PÖFF describes the three countries as individually small but increasingly significant when viewed as a regional film ecosystem, combining experienced crews, competitive incentives and a growing record of international festival success.
The three industries remain structurally modest by European standards, dependant to varying degrees on public funding and international co-production. Yet the past few years have produced a striking concentration of successes: Estonia’s Smoke Sauna Sisterhood (Anna Hints, 2023), Latvia’s Flow (Gints Zilbalodis, 2024), Lithuania’s Toxic and an expanding number of Baltic co-productions at Cannes, Locarno, Berlin and elsewhere. The more interesting question, however, is whether that visibility is being converted into something more durable: larger and more diversified financing pools, stronger production infrastructure, sustainable employment and a domestic audience willing to watch local films.
In that respect, Estonia, Latvia and Lithuania increasingly resemble three variations on the same experiment. Each is trying to use international success and inward investment to strengthen a national cinema that could never survive on market forces alone. But their priorities and their vulnerabilities are not identical.
Estonia: focus on audience
The smallest of the three Baltic nations enters this new phase with perhaps the clearest emphasis on treating cinema as an interconnected system rather than simply a production sector. Estonian Film Institute representative Edith Sepp argues that the post-pandemic shift has been fundamentally audience-driven. Estonians buy around 1.7 cinema tickets per capita, she notes, above a European average of roughly 1.2, but national cinema has yet to regain its pre-pandemic position. Estonian films accounted for 23% of domestic admissions in 2019; that figure fell to 14% in 2025, with a target of returning to 20% by 2028.
For Sepp, this does not mean choosing between national production, international co-production and inward investment. All three have to reinforce each other. Film Estonia’s cash rebate has risen from 30% to as much as 40%, while international interest in shooting and co-producing in the country has increased. Yet, asked to identify the central driver, she returns to domestic cinema: “above all we need our own films for audiences”.
That distinction is important. Estonia is not attempting to turn itself primarily into a service-production territory. Annual national production funding has been around €7 million, according to Sepp. This means that international financing is virtually indispensable for ambitious local work. Co-production relationships have consequently expanded beyond the immediate Nordic-Baltic region towards France, Italy, Ireland and the Balkans. In her words, national money remains “the core, the spine”, but increasingly acts as the foundation on which majority Estonian international co-productions can be constructed.
The larger industrial push is now happening through infrastructure. Estonia lost much of its dedicated film-production infrastructure during the 1990s, a weakness the country is trying to reverse. The Ida Hub in eastern Estonia has opened some 3,200m2 of studio space, while Tallinnfilm Studios – designated an investment of national importance – is expected to add around 3,500m2 when it opens in 2028.
Film Estonia itself has a 2026 budget of €9.2 million, alongside its strengthened rebate. Sepp sees the significance not simply in the number of productions attracted, but in what repeated international shoots can leave behind: trained crews, more experienced companies and longer-term professional relationships. “For me, this is where the real structural impact happens – in people and skills,” she says.
Her caution is equally revealing. Estonia’s challenge is not simply to grow content production, but to prevent a small-language national cinema from disappearing inside it. In other words, the cash rebate and studio expansion are tools; the political and cultural objective remains a recognisably Estonian cinema.
Click here for an overview of Estonian productions and co-productions from the past three years.
Latvia: strong visibility and fragile economics
Meanwhile, Latvia presents a different paradox. Its domestic cinema has arguably never been more visible, yet the financial foundations of the sector remain comparatively fragile. Cinema attendance has still not recovered to its pre-Covid level. Latvia recorded 2.16 million admissions in 2025, compared with 2.72 million in 2019. But within that smaller market, Latvian films increased their share from 20.2% to 24.2%, generating 523,775 admissions, while four national titles reached the country’s annual top 10.
National Film Centre head Dita Rietuma sees that audience performance as significant precisely because it demonstrates that Latvian cinema is not confined to a symbolic cultural niche. At the same time, she argues that domestic box office cannot create a sufficient economic base for a small film industry. Co-production, incentives and incoming shoots therefore fulfil functions that local theatrical revenues cannot.
The obvious emblem is Gints Zilbalodis’s Flow. The Latvian-French-Belgian animated feature transformed a relatively small production into a global cultural event, culminating in an Academy Award. It dramatically increasing international awareness of Baltic animation. But Flow also illustrates why festival and awards success cannot be treated as an industrial policy in itself. Rietuma describes a “considerable gap between cultural visibility and economic scale”.
There are signs that this gap is beginning to narrow. Latvia can offer a cash rebate of up to 30% through the national mechanism, potentially rising higher when combined with other schemes such as the Riga Film Fund. In 2025, 10 foreign projects from seven countries supported through the Latvian Investment and Development Agency were associated with more than €40 million in investment.
Yet Latvia’s position also exposes one of the basic tensions running through all three Baltic industries. Production incentives can bring work, foreign capital and professional development, but they cannot replace selective public support for national films. Rietuma draws a sharp line between the two: one instrument develops national cinema, the other primarily stimulates economic activity.
That matters particularly because Latvia has developed strong creative identities in areas that are not necessarily commercially self-sustaining. Rietuma points to highly skilled crews and established traditions in both animation and documentary filmmaking. The success of Flow may have made Latvian animation newly visible to a mass audience, but it emerged from a much longer culture of independent animation, while documentary production has historically given Latvia an outsized presence on the festival circuit.
The challenge now is to turn exceptional projects into continuity. Latvia has proved that individual films can travel extraordinarily far. The next question is whether producers can consistently retain talent, finance the next generation of films and translate international reputation into a production base resilient enough to survive the years when there is no Flow.
Click here for an overview of Latvian productions and co-productions from the past three years.
Lithuania: auteur cinema meets production economy
Lithuania currently offers perhaps the clearest example of a Baltic industry developing simultaneously in two directions: a highly visible auteur cinema on one side and an increasingly sophisticated international production economy on the other.
Its recent festival record suggests that there is no single dominant Lithuanian genre. What is more recognisable is a strain of visually controlled, author-driven filmmaking, often emerging through shorts before moving into features. Saulė Bliuvaitė’s debut Toxic won Locarno’s coveted Golden Leopard in 2024, whilst Laurynas Bareiša won the Festival’s directing award for Drowning Dry. In early 2026, Andrius Blaževičius won Sundance’s World Cinema Dramatic directing award for How to Divorce During the War.
The country’s short film culture is a vital part of that identity. Lithuania was the country focus at Tampere in 2025, where programmes ranged from a new generation of filmmakers to experimental and poetic cinema and work by Lithuanian women directors. The same year brought an unprecedented Lithuanian presence at Cannes: Sergei Loznitsa’s Lithuanian co-production Two Prosecutors reached the main competition, while filmmakers and producers entered programmes including La Résidence and Producers on the Move.
Documentary remains another visible strand. Aistė Žegulytė’s Holy Destructors premiered in Idfa’s Envision Competition in 2025, winning Best Direction before taking Best Baltic Documentary at Tallinn. Rather than a single specialisation, Lithuania’s distinguishing creative feature may therefore be the density of auteur work across fiction, documentary, shorts and experimental forms, supported by unusually active international co-production.
Alongside this sits a much more explicitly economic success story. Introduced in 2014, Lithuania’s film tax incentive covers up to 30% of a production budget and has channelled more than €133 million from Lithuanian companies into 669 productions. The scheme reached a record in 2025. Lithuanian companies invested €25.6 million through the incentive, 42% more than in 2024. A total of 108 films benefited: 68 domestic productions, 21 co-productions and 19 service projects. Foreign productions spent almost €56 million in Lithuania during the year. National production itself has also expanded: 68 Lithuanian films were produced in 2025, compared with 52 in 2019, while 18 Lithuanian Film Centre-supported films completed last year were international co-productions.
That combination – domestic auteur cinema, European co-production and a serious service-production economy – may be Lithuania’s most distinctive industrial characteristic. Lithuanian Film Centre representative Laimonas Ubavičius argues that the country’s recent festival visibility is increasingly producing consequences beyond recognition alone. Programmers are becoming more familiar with Lithuanian filmmakers and actively asking about forthcoming projects, while producers find more opportunities to connect with sales agents and distributors. “International interest is beginning to translate into distribution and export opportunities,” he says, pointing in particular to a growing number of advance sales to domestic and international VOD platforms.
Yet the same expansion is creating a new imbalance. Ubavičius identifies “the widening gap between direct funding for Lithuanian films and the investment generated through the film tax incentive” as the sector’s biggest constraint over the next three to five years. The Lithuanian Film Centre’s annual budget stood at €11.07 million in 2025, against €25.6 million channelled into productions through the incentive. While the figures represent different forms of support, he argues that they reveal an industry in which “production activity is expanding faster than the public funding available to develop and make Lithuanian films”.
The unresolved question is therefore not whether Lithuania can generate production activity, but how much of that expansion ultimately strengthens Lithuanian cinema itself. Festival breakthroughs are feeding into international distribution, co-production remains unusually active and the incentive is attracting unprecedented levels of private capital. But in an industry this small, the distinction between becoming an efficient place to make films and sustaining a national cinema capable of producing them remains crucial.
Click here for an overview of Lithuanian productions and co-productions from the past three years.
How soon is now?
PÖFF’s 30th-anniversary Baltic focus therefore arrives at an unusually revealing moment. Estonia, Latvia and Lithuania are enjoying a level of international visibility unthinkable just a generation ago. The next stage is less glamorous but more crucial: turning that visibility into institutions, audiences, financing structures and professional careers durable enough to ensure that the current Baltic wave becomes an industry rather than an episode. Could that take another five to 10 years? Or another generation?
The image at the top of this article is from Estonia’s 2025 hit Mo Papa (Eeva Mägi), the other stills are from Two Prosecutors, Drowning Dry, and Holy Destructors.
Tags: 30th Tallinn Black Nights Film Festival, Industry@Tallinn & Baltic Event 2026
This article was originally published in DMovies.org, written by Davide Abbatescianni.